Blog
Best Time to Buy Medigap: 2026 Timing and Enrollment Guide
By Medicare Mentors ·
Missing your Medigap window by even one day could cost you thousands in medical bills for the rest of your life. We understand that Medicare feels like a puzzle with too many pieces, especially when you're bombarded with mailers and conflicting deadlines. It's completely normal to feel anxious about being denied coverage for a pre-existing condition or getting stuck with a plan that doesn't fit your budget. Finding the best time to buy medigap isn't just about a date on the calendar; it's about securing your "Golden Ticket" to lifelong healthcare security.
In this guide, we'll clear up the confusion between Part A and Part B start dates so you don't miss your one-time enrollment window. You'll learn exactly how the 2026 rules affect your choices and why timing your application correctly guarantees you'll never face medical underwriting penalties. We'll walk through the specific timeline for North Carolina residents, from Raleigh to Charlotte, so you can move forward with total confidence. Dave and Michele Johnson have helped thousands of neighbors navigate this transition. We're here to show you that getting the right coverage is simpler and more rewarding than you think.
Key Takeaways
- Secure your "Golden Ticket" by enrolling during the six-month window when insurance companies are prohibited from using your health history to deny coverage.
- Identify the best time to buy medigap based on your specific Medicare Part B start date to avoid lifelong penalties or being locked out of the plan you want.
- Learn how to navigate the transition from employer coverage to Medicare without triggering a gap in your protection or losing your enrollment rights.
- Explore the unique "Guaranteed Issue" rights in North Carolina that protect your ability to switch plans if you move or if your current coverage ends.
- Gain peace of mind by working with local experts who provide education-first, independent advice to compare all available carriers at no cost to you.
What is the Medigap Open Enrollment Period (OEP)?
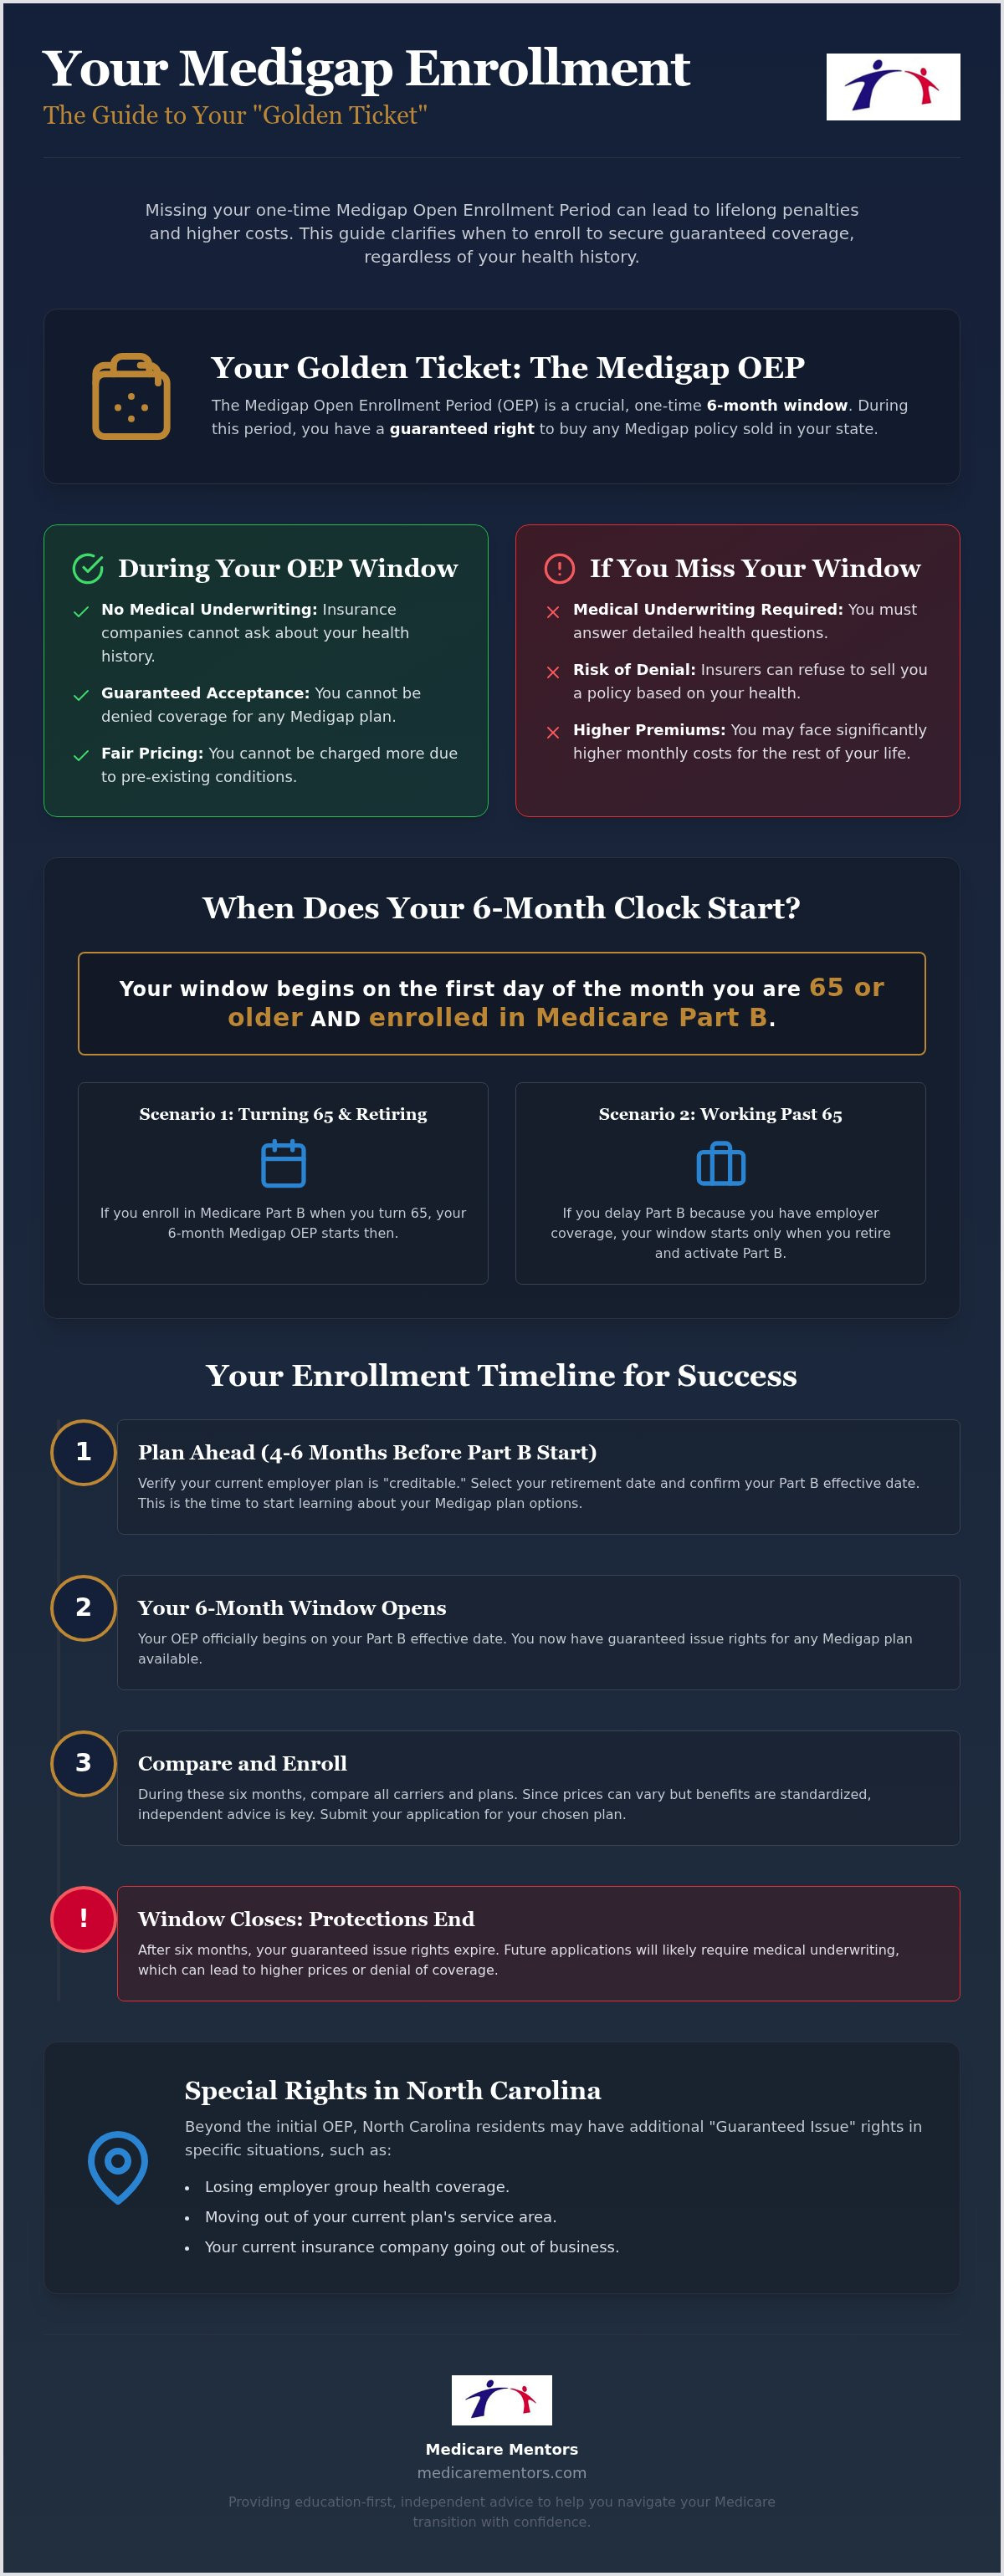
The Medigap Open Enrollment Period is the most critical window in your Medicare journey. It's a six-month period where you have a guaranteed right to buy any Medigap policy sold in North Carolina. During this time, insurance companies can't look at your medical history or charge you more because of health issues. Most people only get this chance once in their lifetime, so understanding the timing is vital for your long-term budget. Dave and Michele Johnson at Medicare Mentors often help neighbors in Raleigh and Durham identify this window early to ensure they don't miss out.
To build a solid foundation, you might ask What is Medigap? and how it differs from other options. It's private insurance designed to pay the costs that Original Medicare leaves behind, like your 20% coinsurance. Because you can choose any plan without a physical exam during your OEP, this is truly the best time to buy medigap.
The Medigap OEP is your "Golden Ticket" to any plan regardless of health history.
To better understand this concept, watch this helpful video:
The 6-Month Window Explained
Your personal clock starts on the first day of the month you're both 65 or older and enrolled in Medicare Part B. It's a common mistake to confuse this with the Annual Enrollment Period (AEP) that happens every fall. While AEP lets you change your Part D drug plan or Medicare Advantage plan, it doesn't give you a free pass to join a Medigap plan without health questions. If you let this six-month window close, you might face much higher premiums or be denied coverage entirely. For those retiring in 2026, the best time to buy medigap is right as your Part B becomes active. We provide our comparison services at no cost to help you track these specific dates.
- Start Date: The first day of the month your Part B begins.
- Duration: Exactly six months from that start date.
- Eligibility: You must be 65 or older to trigger this federal protection.
Why Guaranteed Issue is Your Best Friend
Guaranteed issue rights are your protection against medical underwriting. Normally, insurance companies use underwriting to check your health history, medications, and even your height and weight to decide if they'll cover you. During your OEP, underwriting is completely bypassed. This provides incredible peace of mind for anyone managing chronic conditions like diabetes, heart disease, or past cancer. You get the same price as someone in perfect health. We cover these protections extensively in our Medicare Supplement Insurance: The Complete 2026 Guide to Medigap. Our goal is to make sure you're never locked out of the care you need just because of a pre-existing condition.
Turning 65 vs. Retiring: When Does Your Clock Actually Start?
One of the biggest misconceptions we encounter in Raleigh is the idea that your Medigap window automatically opens on your 65th birthday. While that's true for many, the actual trigger is your enrollment in Medicare Part B. If you're still working and have coverage through a large employer, you might choose to delay Part B. This is a critical distinction because once your Medigap Open Enrollment Period starts, you can't hit the pause button. Enrolling in Part B too early while you still have employer health insurance can accidentally exhaust your one-time "Golden Ticket" window before you even need it.
Finding the best time to buy medigap requires looking at your specific retirement timeline. We recommend this 3-step checklist for timing your transition:
- Verify Creditable Coverage: Check with your HR department to ensure your current group health plan is considered "creditable" by Medicare standards.
- Pick Your Date: Select your firm retirement date at least four months in advance to avoid a rush.
- Coordinate Part B: Set your Part B effective date to begin the very first day your employer coverage ends.
Scenario A: Retiring at 65
For most people, the standard path is the simplest. Your Medicare Part A and Part B usually start on the first day of the month you turn 65. In this case, the best time to buy medigap is two to three months before your birthday. This lead time allows Dave and Michele Johnson to help you compare carriers and ensure your new policy is approved and ready to go the moment your employer plan ends. This proactive approach prevents any stressful gaps in your medical protection.
Scenario B: Working Past 65
If you plan to work until 67, 70, or beyond, you can likely delay Part B without penalty. Your six-month Medigap window remains locked until you eventually activate Part B. When you decide to leave your job, you'll use a Special Enrollment Period (SEP) to sign up for Medicare. Your Medigap OEP starts the very same day your delayed Part B goes live. This ensures you have the same protections as someone turning 65. If you're feeling unsure about your specific situation, personalized Medicare planning can help you map out these dates with precision.
Navigating these dates alone can be overwhelming, but you don't have to do it by yourself. You can reach out to the team at Medicare Mentors to discuss your retirement timeline at no cost.
The Risks of Waiting: Medical Underwriting and the "Lock-In"
Missing your initial six-month window changes the rules of the game. Once that period expires, you lose your federal right to buy a policy without health questions. This shift into "medical underwriting" means insurance carriers will review your medical history, current prescriptions, and sometimes even your height and weight before deciding to offer you a plan. Because you can be denied for health reasons later, the first six months of your Part B enrollment is the absolute best time to buy medigap. Medicare.gov explains the best time to buy is during this protected window to avoid these hurdles.
Underwriting isn't just a formality; it's a risk assessment. If you develop a chronic condition after your window closes, you might find yourself "locked in" to your existing plan. This happens when your health changes enough that no other carrier will accept your application. You could be stuck with high rate increases on an old plan because you no longer qualify to switch to a more competitive one. Waiting past the best time to buy medigap could leave you with fewer choices and higher costs for the rest of your life.
Understanding the Health Questionnaire
If you apply for Medigap outside of your protected window, you'll likely face a multi-page health survey. Common conditions like insulin-dependent diabetes, recent heart procedures, or even upcoming surgeries can lead to an immediate denial. Outside of your OEP, carriers can also charge you significantly higher premiums based on your health status. This is why we encourage our neighbors in Durham and Raleigh to choose a robust, long-term option like Plan G during their initial enrollment. Dave and Michele Johnson focus on helping you select a plan that you'll be happy with for the next twenty years, not just the next twenty months.
The Annual Enrollment Period (AEP) Myth
A common point of confusion we hear is the belief that you can switch Medigap plans every fall. This is simply not true. The Annual Enrollment Period (Oct 15 - Dec 7) allows you to change your Part D drug plan or your Medicare Advantage plan, but it provides no "free pass" for Medigap. Changing your Supplement plan is a year-round possibility, but it almost always requires passing health questions once your initial window is gone. To help you stay on top of your coverage, Medicare Mentors provides annual reviews to check your plan's rate stability and ensure you aren't paying more than you should.
Special Situations: Guaranteed Issue Rights in North Carolina
While we've established that the initial six-month window is the best time to buy medigap, life doesn't always follow a straight path. Certain life events trigger "Guaranteed Issue" (GI) rights, which act as a safety net. These rights force insurance companies to sell you a policy without asking a single health question, even if your initial enrollment period ended years ago. Common triggers include your current insurance company going bankrupt, moving out of your plan's service area, or losing health coverage through no fault of your own.
For many people, moving to the Raleigh, Durham, or Charlotte areas from out of state is a strategic moment to review their healthcare. If you move from a state where your current plan isn't available, you may have a limited window to secure a new Medigap policy here in North Carolina without underwriting. Dave and Michele Johnson frequently work with retirees relocating to the Triangle who are surprised to find that their move granted them a fresh start with their supplemental coverage.
Losing Employer Coverage After 65
If you worked past 65 and finally decided to retire, you have a 63-day window to secure a Medigap plan after your group coverage ends. This is a high-stakes timeline. Many people mistakenly believe they can wait until their COBRA coverage ends, but Medicare rules are different. COBRA is not usually considered "creditable coverage" for Medigap GI rights. If you wait for COBRA to run out, you might miss your 63-day window and be forced to undergo medical underwriting. You must act quickly once your active employment coverage stops to ensure you don't lose these protections.
The Medigap Trial Right
The "Trial Right" is essentially a 12-month test drive for Medicare Advantage. If you joined a Medicare Advantage plan when you first became eligible for Medicare at 65, you have exactly one year to change your mind. If you decide the network is too restrictive or the co-pays are too high, you can switch back to Original Medicare and buy a Medigap plan with no health questions asked. This is a powerful tool for those who feel they may have chosen the wrong path initially. You can learn more about these options in our guide on Medicare Advantage vs. Original Medicare: Key Differences. Understanding these specific rules ensures you don't miss the best time to buy medigap for your unique situation.
If you're facing one of these transitions and aren't sure if you qualify for a GI right, you can schedule a no-cost consultation with our team to explore your North Carolina options.
How Medicare Mentors Times Your Enrollment for Success
Dave and Michele Johnson founded Medicare Mentors with a simple, foundational idea: you deserve a protective advocate, not a high-pressure salesperson. We believe that understanding your options is the first step toward long-term peace of mind. As independent brokers, we aren't tied to any single insurance carrier. This independence is our commitment to objectivity. It allows us to compare every available plan in North Carolina to find the one that truly fits your budget and lifestyle. We act as your ally, ensuring you have the information needed to make a choice that protects your health and your wallet.
Our services are provided at no cost to you because we're compensated by the insurance carriers. This relationship-focused support doesn't stop at your Supplement plan. We also help you build a complete safety net by comparing dental, vision, and hearing plans, along with critical illness protection for cancer, heart attack, and stroke. We even assist with final expense insurance to ensure your family is protected from every angle. Our model includes annual coverage reviews to ensure your plan remains competitive as rates change over time in the Raleigh or Durham area.
Our Teacher-Student Approach
We prioritize explaining the "why" before we ever discuss the "what." This teacher-student dynamic is at the heart of everything we do. For our neighbors in the Triangle, this means looking closely at how local hospital network shifts might affect your access to specific doctors or facilities. We move at your pace, not a sales pace. If you need multiple conversations to feel confident in your decision, we'll take that time with you. Our goal is to lower your anxiety by providing a safe, low-pressure environment where you can seek objective advice without feeling rushed.
Ready to Secure Your Golden Ticket?
Timing is vital for your "Golden Ticket" of guaranteed coverage. While the six months after your Part B starts is the primary window, the conversation should ideally begin much earlier. We recommend reaching out at least six months before you turn 65 or your planned retirement date. This gives us plenty of time to build your customized plan and answer every question without the stress of a looming deadline. Identifying the best time to buy medigap is a multi-piece task, but you don't have to assemble it alone.
We're here to be your patient educators throughout the entire process. Whether you're retiring from a long career in Charlotte or finally transitioning off an employer plan in Raleigh, we'll ensure your enrollment is handled with integrity. We're ready to meet you in your preferred environment to help you move forward with total confidence in your coverage.
If you're ready to take the next step and secure your future healthcare, schedule your free Medicare planning session here. Dave and Michele are ready to help you navigate your transition with ease.
Secure Your Future Healthcare Today
Identifying the best time to buy medigap is the single most important step you can take to protect your retirement savings. You've learned that your six-month "Golden Ticket" window starts the moment your Part B goes live, whether that's at age 65 or when you finally leave the workforce. By acting during this protected time, you bypass health questions and guarantee yourself the most comprehensive coverage available in North Carolina. Waiting even a month too long could lead to medical underwriting and higher costs later in life.
Dave and Michele Johnson are here to ensure you don't have to navigate these deadlines alone. As independent brokers with almost 300 five-star reviews, we provide unbiased comparisons from every major carrier to find your perfect fit. Our education-first approach means we work as your partners, offering relationship-focused lifetime support at no cost to you. Ready to assemble your Medicare plan with confidence? You can book your free Medigap consultation with Dave and Michele to get started. We're excited to help you step into this next chapter with the security and peace of mind you deserve.
Frequently Asked Questions
Can I buy a Medigap policy at any time of the year?
You can apply for a policy at any point during the year. Unlike Medicare Advantage or Part D plans, Medigap doesn't have a restricted annual window for applications. However, applying outside of your initial six-month enrollment period usually means you'll have to answer health questions. Insurance companies in Raleigh or Charlotte can use these answers to charge you more or deny your application entirely based on your medical history.
What happens if I miss my Medigap Open Enrollment Period?
Missing this window means you've passed the best time to buy medigap without health questions. Once this one-time, six-month period ends, you lose your "guaranteed issue" rights. You'll likely face medical underwriting, where carriers review your prescriptions and past surgeries. If you have chronic conditions like heart disease or diabetes, you might be "locked in" to your current coverage because other companies won't accept your new application.
Do I need to buy Medigap if I have a Medicare Advantage plan?
No, you cannot have both at the same time. These two types of coverage work very differently and it's actually illegal for an agent to sell you a Medigap policy if they know you're staying on a Medicare Advantage plan. Medigap is designed specifically to fill the gaps in Original Medicare. If you want to switch from Advantage to a Supplement plan, you'll typically need to wait for a valid enrollment window.
Is there a "birthday rule" for Medigap in North Carolina?
North Carolina does not currently have a "birthday rule" for Medigap plans. Some states allow residents to switch to a similar plan around their birthday each year without health questions, but that isn't the law here. Whether you're in Durham or Greensboro, you'll generally need to pass medical underwriting if you want to change your Supplement plan after your initial six-month window has closed. We'll help you monitor local legislative changes annually.
If I am still working at 65, when is the best time to buy Medigap?
The best time to buy medigap is during the six months immediately following your enrollment in Medicare Part B. If you have "creditable" coverage from a large employer, you can often delay Part B without penalty. Your Medigap clock won't start ticking until you actually retire and activate that Part B coverage. We recommend starting the planning process with Dave and Michele Johnson about six months before your planned retirement date.
Can a Medigap company cancel my policy if I develop a health condition later?
Your policy is "guaranteed renewable," which means the insurance company cannot cancel it just because your health changes. As long as you pay your premiums on time and were truthful on your original application, the carrier must keep you covered. This protection provides vital peace of mind for our neighbors in Fayetteville and Wilmington. Even if you develop a serious illness years after joining, your coverage stays exactly where it is.
How much does it cost to use a Medicare broker like Medicare Mentors?
Our expert guidance and lifetime support are provided at no cost to you. Medicare Mentors is an independent brokerage, and we're compensated directly by the insurance carriers when we help you enroll. You'll pay the exact same premium whether you go through us or try to navigate the carriers alone. Dave and Michele Johnson focus on education first, ensuring you get unbiased comparisons of all North Carolina plans without any hidden fees.
What is the difference between a Medigap Open Enrollment Period and the Annual Enrollment Period?
The Medigap Open Enrollment Period is a one-time, six-month window triggered by your Part B start date. It's your only "free pass" to join any plan without health questions. The Annual Enrollment Period happens every year from October 15 to December 7. AEP is specifically for changing Medicare Advantage or Part D prescription plans. It does not give you a guaranteed right to switch your Medigap plan without undergoing medical underwriting first.