Blog
Medigap Birthday Rule in North Carolina: Your 2026 Guide to Switching Plans
By Medicare Mentors ·
What if the "locked-in" feeling you have about your Medicare Supplement plan is actually based on a myth? You might see your monthly premiums climbing every year and worry that a heart condition or diabetes means you're stuck with your current carrier forever. Many people search for the medigap birthday rule north carolina hoping for a simple way to switch, only to find conflicting information that leaves them more confused than when they started.
We understand how stressful it is to balance a fixed budget against rising healthcare costs. It's true that North Carolina doesn't have a state-mandated annual window like some other states, but that isn't the whole story. In this guide, we'll show you the truth about North Carolina's regulations and reveal specific carrier policies that act as hidden doors. These rules often allow you to switch to a lower-cost plan without answering a single health question or undergoing medical underwriting.
You'll learn exactly how to navigate these 2026 options to find the best value for your specific situation. We'll compare the latest trends for Plan G and Plan N, explain how your initial enrollment window impacts your future, and provide a clear roadmap to help you lower your monthly expenses with the help of a local expert who puts your needs first.
Key Takeaways
- While North Carolina doesn't have a formal state-mandated medigap birthday rule north carolina residents can still find "hidden" windows to switch plans without health questions.
- You can often bypass medical underwriting by using specific carrier rules, such as internal transfer policies or seasonal underwriting holidays offered by certain insurers.
- Learn which life events, like losing employer-sponsored retiree health coverage, trigger a legal right to switch Medigap plans regardless of your health history.
- Identify the exact steps to review your current rate hikes and compare them against 2026 market prices to ensure you aren't overpaying for the same coverage.
- Discover how a local, no-cost review can help you navigate these complex rules and secure a plan that protects both your health and your budget.
Does North Carolina Have a Medigap Birthday Rule in 2026?
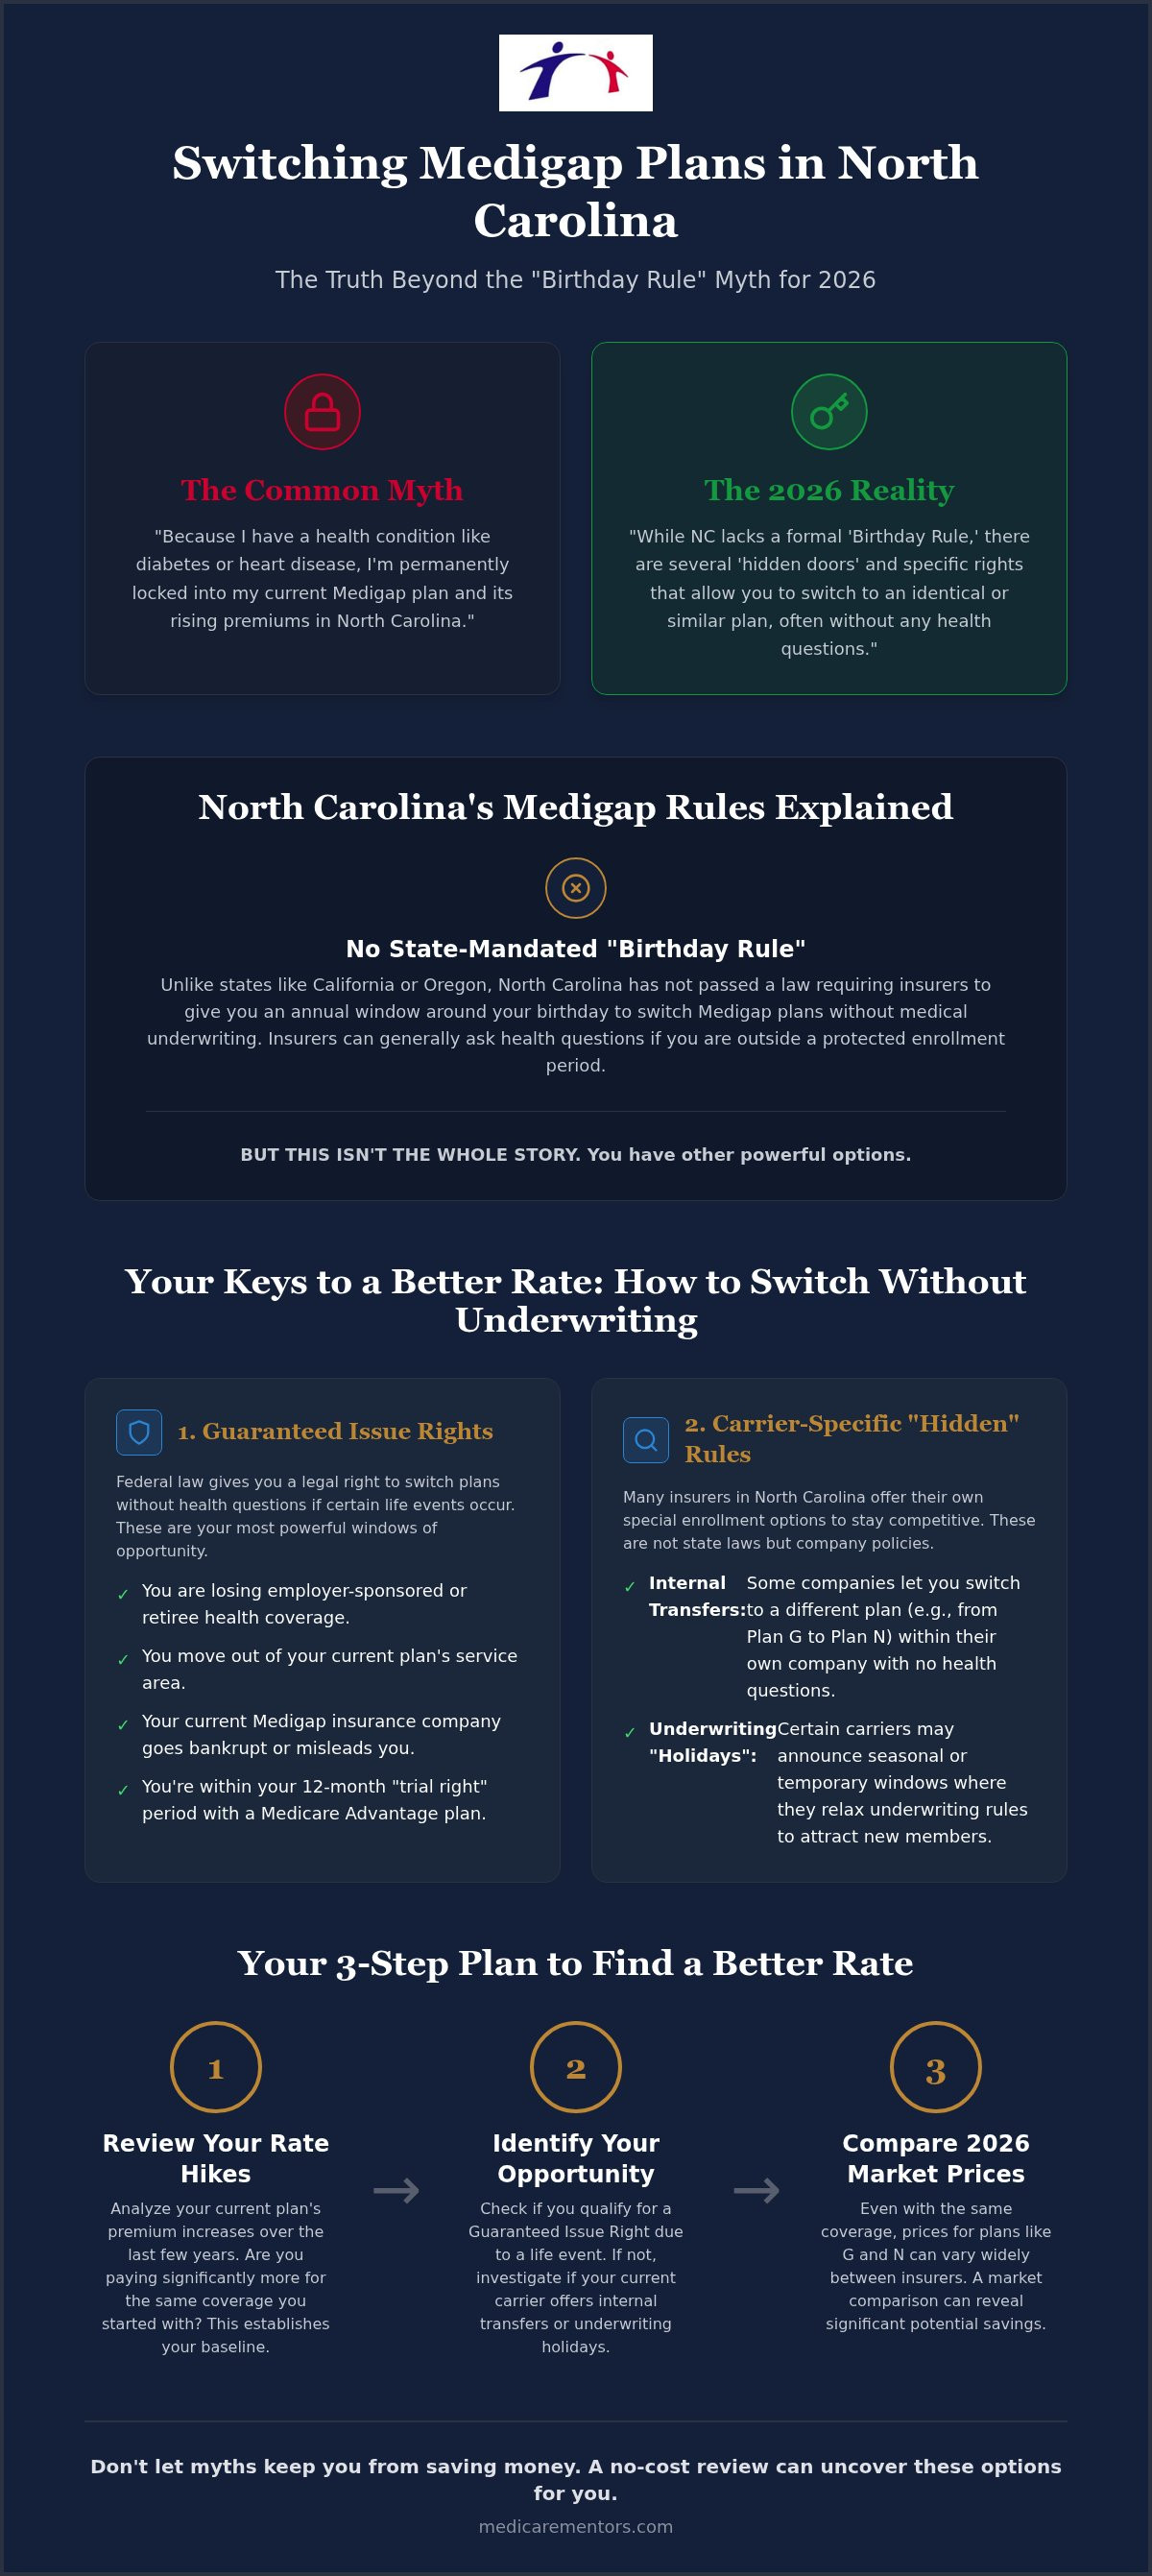
If you're looking for a quick "yes" or "no" answer, here is the reality: North Carolina does not currently have a state-mandated Medigap Birthday Rule. Unlike states such as California or Oregon, our state legislature hasn't passed a law requiring insurance companies to let you switch plans every year just because you had a birthday. For 2026, the North Carolina Department of Insurance (NCDOI) continues to follow standard federal guidelines. This means most residents must answer health questions to change their coverage after their initial enrollment period ends.
To help you understand how these rules vary, it's useful to look at what Medigap (also called Medicare supplement insurance) actually provides. These plans are designed to fill the "gaps" in Original Medicare, but the rules for moving between them are set at the state level. In NC, the focus remains on traditional enrollment windows rather than an annual birthday reset.
To better understand this concept, watch this helpful video:
What Exactly is a Medigap Birthday Rule?
In states that have this rule, beneficiaries get a "Guaranteed Issue" window that opens for a short time around their birthday. During this window, you can switch to a plan with "equal or lesser" benefits without going through medical underwriting. This is a massive benefit for seniors with chronic conditions like heart disease or diabetes who would otherwise be denied a new plan. It allows them to shop for lower premiums without the fear of being rejected due to their medical history.
The Current Situation in North Carolina
North Carolina prioritizes market stability. By not having an annual switching window, the state aims to keep premiums more predictable for everyone. While you can always reach out to the Seniors' Health Insurance Information Program (SHIIP) for free counseling, their advisors will confirm that no automatic birthday window exists here for 2026. While the specific medigap birthday rule north carolina seniors often hear about in other states is absent, residents here still have several legal paths to switch their coverage.
Many people believe the "locked-in" myth. They think they're stuck with a plan that has skyrocketing premiums just because they have a health condition. This isn't true. We focus on helping you find specific carrier rules and trial rights that allow for a change. If you're feeling overwhelmed, starting with a comprehensive medicare planning session can help identify these hidden opportunities. You don't have to navigate these complex state rules alone.
Understanding Medigap Switching and Underwriting in NC
Because there isn't a state-mandated medigap birthday rule north carolina residents must usually navigate medical underwriting to change their coverage. This process is how private insurance companies assess your health to decide if they'll accept your application. According to the North Carolina Department of Insurance, insurers can generally review your health history and even deny coverage if you're outside of a protected enrollment window. Understanding these rules is the first step toward taking control of your monthly premiums.
Medical Underwriting: The Standard Rule
Carriers in NC use underwriting to manage their risk. They'll ask about your history with chronic illnesses like COPD, recent hospitalizations, or active cancer treatments. Common triggers for a denial include things like pending surgeries or the use of certain high-cost medications. If you're worried about your history, don't rush into a formal application. We often perform "pre-liminary underwriting" for our clients. By having an informal conversation with us first, we can find out which carriers have more flexible standards for your specific health needs. This protects you from having a formal denial on your insurance record while helping us find a path forward.
Your One-Time Medigap Open Enrollment
Your initial Open Enrollment Period is your most valuable asset. This six-month window starts on the first day of the month you're both 65 or older and enrolled in Medicare Part B. During this time, you have a "no-questions-asked" right to join any Medigap plan available in the state. No carrier can charge you more or deny you based on your health history. It's the only time you're 100% guaranteed the best rates regardless of whether you have diabetes or a heart condition. For a deeper look at how these plans differ, check out our Medicare Supplement Insurance: The Complete 2026 Guide to Medigap.
Most carriers also use a six-month "look-back" period for pre-existing conditions. If you were treated for a health issue in the six months before your new plan starts, the company might wait up to six months before covering costs related to that specific condition. However, if you're switching from one creditable coverage plan to another, this waiting period is often waived. If you're feeling stuck, a quick medicare planning review can help you determine if you're eligible to save money without the stress of a health exam.
Guaranteed Issue Rights: When You CAN Switch in NC
Since there isn't a standard medigap birthday rule north carolina beneficiaries can use every year, you have to look for "Guaranteed Issue" (GI) rights instead. These rights act as a legal safety net. They ensure you can buy a policy even if you have serious health problems. Think of these as specific "hall passes" that let you bypass the medical underwriting we discussed earlier. They're designed to protect you when your coverage changes through no fault of your own.
One common trigger is losing your employer-sponsored retiree health coverage. This happens often in North Carolina as companies restructure their benefits or end retiree plans. Another scenario involves your current Medigap company. If they go bankrupt or stop offering coverage in the Tar Heel state, you have a legal right to find a new plan. According to the official U.S. government site for Medicare, these protections are vital for maintaining continuous coverage without price penalties.
Timing is everything when it comes to these rights. You generally have a 63-day window from the date your coverage ends to apply for a new plan under GI rules. If you wait until day 64, that legal protection disappears. Moving can also be a catalyst. If you move into a new service area, such as relocating to Raleigh or Charlotte, and your current plan isn't available in your new zip code, you may gain a special window to switch your coverage.
The 'Trial Right' for Medicare Advantage
If you're curious about different types of coverage, you might consider using a "trial right." This allows you to join a Medicare Advantage plan for the first time and "test drive" it for up to 12 months. If you decide it isn't the right fit for your lifestyle or doctor preferences, you have a legal right to return to a Medigap plan without answering any health questions. It's a low-pressure way to explore your options. To see how these plans compare, you can read The Ultimate Guide to Medicare Advantage Plans in 2026.
Retiring Past 65 in North Carolina
Many professionals in the Research Triangle Park (RTP) area continue working well past age 65. If you have active employer coverage, you likely delayed your Medigap enrollment. When you finally decide to retire at 70 or 75, losing that active employer plan triggers a special window. You'll need specific documentation from your HR department to prove your right to switch. We often help retirees gather these forms to ensure their transition to Medicare is smooth and predictable. This allows you to move into retirement with the peace of mind that your health costs are controlled.
Carrier-Specific 'Hidden' Rules: The NC Advantage
While we've established that there isn't a state-mandated medigap birthday rule north carolina residents can use, some insurance companies have created their own internal versions. These carrier-specific policies are often the most overlooked tools for lowering your monthly costs. Insurance companies sometimes offer "underwriting holidays" to attract healthy new members or encourage loyalty. During these limited windows, a carrier might waive health questions entirely. This creates a perfect opportunity to lower your premium and reallocate those savings toward a dental and vision plan to cover the things Medicare doesn't.
These "hidden" windows are often off-cycle, meaning they don't align with the standard fall enrollment period. Because these rules aren't found in federal handbooks, having an advocate who tracks these private shifts is essential. We monitor these changes across the state to ensure our neighbors aren't overpaying for the same coverage they could get elsewhere for less.
Blue Cross Blue Shield of NC Internal Policies
In our state, Blue Cross Blue Shield of North Carolina (BCBSNC) offers what many consider the closest thing to a medigap birthday rule north carolina has to offer. Their "Blue-to-Blue" policy often allows current members to move between different Medigap plans without a full medical exam. This is a massive benefit if you're stuck in an older, "closed block" plan like Plan F. As these older plans stop taking new members, the premiums often spike. Moving to a modern Plan G through an internal policy can save you significant money. Those savings could easily fund a heart attack or stroke policy, providing a cash benefit that protects your retirement nest egg from unexpected medical crises.
Why Annual Reviews are Essential in NC
We constantly track rate increases across Raleigh, Durham, and Charlotte zip codes to see which carriers are still offering the best value. During an annual review, we also help you weigh the pros and cons of moving from Plan G to Plan N. Plan N often features premiums that are $30 to $50 lower each month. If you're healthy, that extra cash can be used to secure final expense coverage, ensuring your family isn't left with a financial burden later. To understand why having a professional eye on these details matters, read Why Use a Medicare Broker? 5 Reasons to Skip the Stress in 2026.
Finding these "hidden" windows requires a teacher-student approach where we show you the data behind carrier choices. We want to help you build a complete safety net that includes cancer protection and other vital supports. If you're ready to see if you qualify for a carrier-specific switch, you can schedule your no-cost plan review today to explore your 2026 options.
How to Review and Switch Your NC Medigap Plan with Confidence
Since the official medigap birthday rule north carolina residents often hope for isn't in place, the responsibility of finding savings falls on you. However, you don't have to do this alone. Moving from a plan with skyrocketing premiums to a more affordable option is a step-by-step process. By following a methodical approach, you can lower your monthly costs without the fear of losing the coverage you rely on. Here is how we guide our neighbors through this transition.
- Step 1: Locate your current renewal notice. This document usually arrives 30 to 60 days before your plan anniversary. It identifies your next rate hike, which is the perfect trigger to see if you're overpaying.
- Step 2: Check for Guaranteed Issue triggers. As we discussed earlier, look for events like plan terminations or losing employer coverage. These are your "hall passes" to skip health questions.
- Step 3: Conduct a preliminary underwriting check. Before you submit a formal application, Dave and Michele Johnson can perform an informal health review. This protects your record from a formal denial.
- Step 4: Compare all NC carriers in your zip code. Rates in Raleigh can differ significantly from those in Charlotte. We look at every available carrier to find the best value for your specific location.
The Medicare Mentors 'Teacher-Student' Approach
We believe that an informed client is a confident client. Our relationship with you is built on a teacher-student dynamic where we provide unbiased comparisons without any high-pressure sales tactics. While a Medigap plan is the foundation of your coverage, we also help you identify other missing pieces in your "healthcare puzzle." This includes exploring options for dental, vision, and hearing plans, as well as specialized protection for cancer, heart attack, and stroke that Medigap doesn't cover. We can even discuss final expense coverage to ensure your family is protected long-term. You can learn more about our holistic philosophy through our Medicare Planning Services.
Take Action: Schedule Your 2026 Medigap Review
Don't wait for your birthday to find a better deal; the best time to review your coverage is about 60 days before your current plan's anniversary. We pride ourselves on being accessible to every senior in the Tar Heel state. Whether you prefer to meet in person, over the phone, or via a video call, we make the process easy and low-stress. When you're ready to talk, please have your current plan name, your monthly premium amount, and a list of your medications ready. We've helped hundreds of North Carolinians find peace of mind, and we'd be honored to do the same for you. Schedule your free NC Medigap review with Dave and Michele Johnson today to see how much you could save in 2026.
Secure Your Peace of Mind for 2026
Navigating the complex details of the medigap birthday rule north carolina requires more than just a quick search. It takes a dedicated partner who understands the local landscape. While our state doesn't offer a mandated annual window, we've shown you that options like carrier underwriting holidays and trial rights are very real. You don't have to accept skyrocketing premiums as a permanent part of your retirement. By understanding the "Blue-to-Blue" rules and tracking your renewal notices, you can protect your budget while keeping the high-quality care you deserve.
We are independent brokers serving all of North Carolina, and we're here to act as your advocate. Dave and Michele Johnson provide the personalized service you need to feel confident in your decisions. With nearly 300 Five-Star Reviews from local seniors, our teacher-student approach ensures you never feel pressured or confused. We're ready to help you piece together the right plan for your unique situation, whether you live in Raleigh, Charlotte, or anywhere in between.
Don't let another rate increase catch you off guard. Book Your Free 2026 Medigap Review today and discover the savings you might be missing. You have the power to secure your health and your financial future, and we're honored to walk beside you every step of the way.
Frequently Asked Questions
Does North Carolina have a Medigap birthday rule?
No, North Carolina does not currently have a state-mandated medigap birthday rule north carolina residents can use every year. Unlike states like California or Oregon, our state legislature hasn't passed a law requiring carriers to offer an annual switching window. This means that for most residents, changing your plan after your initial enrollment period will require you to answer health questions through medical underwriting.
Can I switch Medigap plans at any time in North Carolina?
You can apply to switch your Medigap plan at any time during the year because these plans don't have a restricted enrollment season. The main hurdle is that most insurance companies in North Carolina will require you to go through medical underwriting if you are outside of a protected window. If you're healthy, you can shop for a lower rate whenever you find a better price for the same coverage.
What happens if I apply for a new Medigap plan and get denied?
If a new insurance company denies your application due to your health history, you simply keep your current plan. A denial from a new carrier doesn't cancel or change your existing coverage in any way. To avoid the frustration of a denial, we recommend a preliminary health review. We can often determine which carriers are likely to accept your application before you ever submit a formal request.
Is there an annual Medigap open enrollment period in NC?
No, there isn't an annual open enrollment period for Medigap plans in North Carolina. Many people confuse the fall Annual Enrollment Period with a time to switch Supplement plans without health questions, but that window only applies to Medicare Advantage and Part D plans. For Medigap, your only guaranteed "no-questions" window is the six months after you first enroll in Medicare Part B at age 65 or older.
Does Blue Cross Blue Shield of NC have a birthday rule?
Blue Cross Blue Shield of NC does not have a formal medigap birthday rule north carolina policy, but they do offer internal "Blue-to-Blue" transfer rights. These rules often allow current members to move between different BCBSNC plans without a full health exam. This is a unique advantage that can help you move from an older, more expensive plan to a modern one with lower premiums while staying with the same carrier.
Can I switch from Medicare Advantage back to Medigap in NC?
You can switch back, but you'll typically need to pass medical underwriting unless you are using a specific "trial right." If you joined Medicare Advantage for the first time and want to return to Medigap within 12 months, you have a legal right to do so without health questions. Outside of that 12 month window, carriers in North Carolina can review your medical records before deciding to accept your application.
Why are my Medigap premiums increasing so much in North Carolina?
Most plans in North Carolina use "attained-age" rating, which means your monthly premium naturally increases as you get older. Additionally, if you are in an older plan like Plan F, you might be in a "closed block" of business. Since no new, younger members can join those plans, the remaining group gets older and uses more medical services. This causes the insurance company to raise rates to cover those rising costs.
What is the best Medigap plan for someone living in Raleigh or Charlotte?
Plan G and Plan N are currently the most popular choices for residents in Raleigh and Charlotte. Plan G offers the most comprehensive coverage, leaving you with only the Part B deductible to pay out of pocket each year. Plan N is a fantastic lower-cost alternative if you don't mind small copays for office visits. The best plan for you depends on your health needs and how often you visit your doctor.